 Maya Rivera
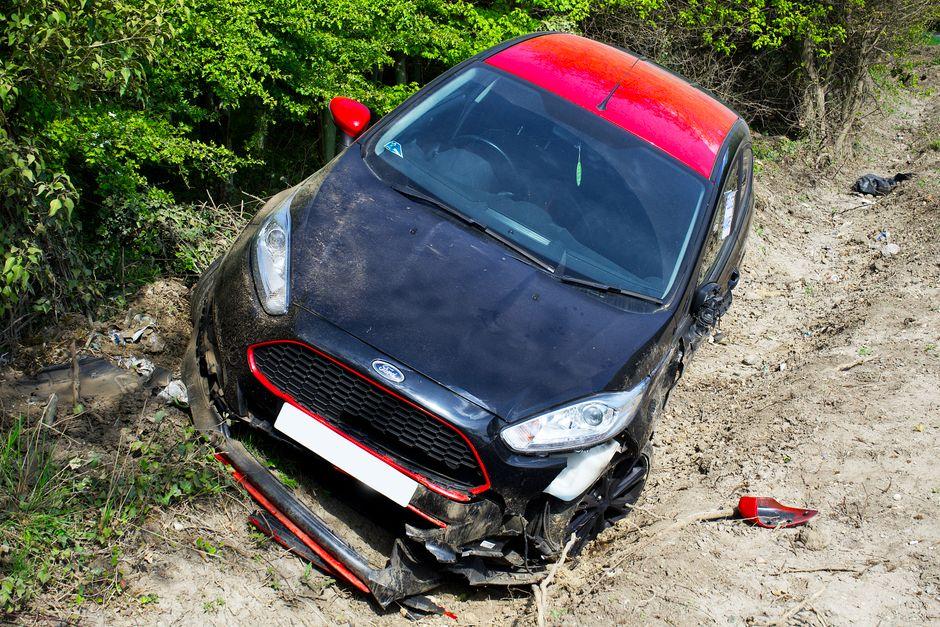
You’re sitting in a crumpled car on the side of the highway. Your hands are shaking. Someone just rear-ended you at 45 mph, and your neck already feels wrong. In the next 60 minutes, you’ll make decisions that could either protect your health and your legal rights or quietly destroy both. Most people have no idea what those decisions are. I spent 12 years on the insurance side watching injury victims make the same costly mistakes over and over, and I switched careers specifically to help people avoid them.
Get Safe, Get Help, Get Documented, In That Order
The first few minutes after a crash are chaotic. Your brain is flooded with adrenaline, which means you might feel completely fine even if you’re seriously hurt. Adrenaline masks pain. That’s not a metaphor; it’s basic physiology. Soft tissue injuries, internal bleeding, and even traumatic brain injuries can feel like nothing immediately after impact.
Start by checking yourself and your passengers for obvious injuries without moving anyone who might have a spinal injury. If anyone is unconscious, bleeding heavily, or has trouble breathing, call 911 immediately. That’s non-negotiable.
If you can move safely, get out of traffic. Turn on your hazard lights. Set up flares or reflective triangles if you have them.
Call 911 even if the accident seems minor. A police report is foundational. Without it, it’s your word against the other driver’s, and insurance companies know exactly how to exploit that gap. I’ve seen adjusters use the absence of a police report to cut settlement offers by 50% or more.
While you wait, document everything. Take photos of both vehicles from multiple angles, the position of the cars before they’re moved, any skid marks, road conditions, traffic signals. Your phone’s timestamp and GPS metadata are quietly building your evidence record every time you snap a picture.
What to Say (and What Not to Say) at the Scene
Helpful resource: Pendaflex Portable File Box for Legal Documents is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
Here’s where people get into trouble fast. You’re shaken, you’re polite, and someone walks over and says “are you okay?” The natural response is “I’m fine.” Don’t say that.
You’re not being deceptive if you don’t know yet. You genuinely don’t know whether you’re fine. Say something like “I’m not sure yet” or “I need to get checked out.” It’s honest and it doesn’t create a recorded statement you’ll regret later.
Talk to the police officer and give a factual account of what happened. Stick to what you observed, not what you think or feel about fault. You don’t need to analyze who caused the accident on the scene; that’s what insurance investigators and sometimes courts do.
Exchange information with the other driver: full name, license number, insurance company, policy number, and vehicle registration information. Get the names and contact information of any witnesses before they leave. Witnesses disappear fast.
Do not apologize. Even a casual “I’m sorry, I didn’t see you coming” can be characterized as an admission of fault later. This isn’t about being cold; it’s about protecting yourself from having your own words used against you.
Seek Medical Attention, Even If You Feel Okay
Go to the emergency room or urgent care the same day if possible. If you can’t do same-day, get there within 24 to 48 hours at the absolute latest.
Delay creates two problems. First, some injuries get worse. Whiplash, herniated discs, and concussions can seem mild for days before becoming debilitating. Second, the insurance company will argue your injuries weren’t caused by the accident because you didn’t seek treatment right away. I’ve watched adjusters write internal notes that said something like “claimant waited 10 days, likely pre-existing or unrelated.” That note influences every subsequent offer.
Tell your doctor specifically that you were in a car accident, what your symptoms are, and where your pain is located. Be thorough. If you have a headache, say so. If your lower back is stiff, say so. Anything not documented in that initial visit doesn’t officially exist from the insurance company’s perspective.
Follow through on every treatment your doctor recommends. Missing physical therapy appointments or skipping follow-up visits creates gaps in your medical record that adjusters use to argue you weren’t really that injured.
Keep a detailed injury journal. Write down your pain levels, your limitations, how you slept, what activities you couldn’t do. This personal documentation becomes powerful evidence of how the injury affected your daily life. A good injury documentation journal can keep all of this organized in one place (disclosure: this site may earn a small commission on Amazon purchases). If you want a more structured approach to managing your records, check out these tips on how to document injuries after an accident.
Dealing With the Insurance Company
The other driver’s insurance company will contact you. Sometimes within hours of the accident. They’re not calling to help you. They’re calling to gather information that limits what they’ll have to pay.
You are not required to give a recorded statement to the other driver’s insurance company. In most states, you have no legal obligation to speak with them at all before consulting with an attorney. That recorded statement is a tool they use to get you to minimize your injuries or contradict yourself later.
You are required to report the accident to your own insurance company, usually within a specific timeframe outlined in your policy. Check your policy or call your agent to understand your obligations.
When the other insurer makes an offer, don’t accept it without understanding what you’re giving up. Accepting a settlement means signing a release, which permanently closes your claim. If your back injury turns out to need surgery six months later, that earlier settlement is gone. The Insurance Information Institute notes that settlements are legally binding agreements, which is exactly why understanding the full scope of your injuries before settling is critical.
To understand how adjusters actually calculate offers, this article on how insurance companies calculate settlements breaks down the math in plain terms.
Step-by-Step: The First 30 Days After a Car Accident Injury
Use this as a checklist.
Day 1:
- Call 911 and file a police report
- Document the scene with photos and witness information
- Seek medical attention; describe all symptoms in detail
- Report the accident to your own insurance company
- Write down everything you remember about the accident while it’s fresh
Days 2 to 5:
- Request a copy of the police report (usually available within a few days)
- Continue all prescribed medical treatment
- Begin your daily injury journal
- Avoid posting about the accident on social media (yes, adjusters check)
Days 6 to 14:
- Gather all medical bills and receipts related to the accident
- Track any lost wages; your employer can provide documentation. Learn more about lost wages in personal injury settlements because this is money many people leave on the table
- Consult with a personal injury attorney, most offer free consultations
- Do not give a recorded statement to the other driver’s insurer without legal guidance
Days 15 to 30:
- Continue medical treatment and documentation
- Begin compiling a demand package if you’re handling the claim yourself, or work with your attorney
- Research what factors might increase or decrease your claim’s value; understanding the factors that increase settlement value can make a real difference in what you ultimately recover
When You Should Seriously Consider Hiring an Attorney
People think attorneys are only for catastrophic accidents. That’s wrong, and it costs people money.
You should strongly consider speaking with a personal injury attorney if: your injuries required more than basic urgent care, your medical bills are above a few thousand dollars, you’re missing work, liability is disputed, or the insurance company is being unresponsive or aggressive.
According to Nolo’s personal injury resources, claimants who hire attorneys typically recover significantly more money than those who handle claims alone, even after attorney fees, particularly in cases involving serious injuries. Most personal injury attorneys work on contingency, meaning they take a percentage of your settlement instead of charging upfront. You pay nothing unless you win.
You should also understand that personal injury cases have statutes of limitations, meaning legal deadlines. Miss the deadline and your right to sue is gone forever. In most states that deadline is two to three years from the accident date, but it varies. Don’t assume you have unlimited time.
If you’re unsure whether your situation qualifies, this resource on whether you have a personal injury case can help you think it through.
The days after a car accident injury are overwhelming, and it’s easy to make decisions that feel right in the moment but create real problems down the road. Taking the scene seriously, getting proper medical care, keeping detailed records, and understanding how insurance companies operate puts you in a fundamentally different position than someone who just wings it. You don’t have to be an expert. You just have to know enough not to be taken advantage of, and now you do.
This article is for general informational purposes only and does not constitute legal advice. Laws vary by state. Consult a licensed personal injury attorney in your jurisdiction for advice specific to your situation. Most personal injury attorneys offer free consultations.
Sources
- Pendaflex Portable File Box for Legal Documents
- injury documentation journal
- Smead Accordion Expanding File Folder for Legal Files
- How to Win Your Personal Injury Claim by Joseph Matthews (Nolo)
- Victim to Victory: A Personal Injury Survival Guide
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Victim to Victory: A Personal Injury Survival Guide (~$16), Written by a personal injury attorney, explains the full claims process, how insurance companies calculate settlements.
- Navigating Personal Injury Claims (~$14), Covers the pre-litigation claims process step by step, medical documentation, negotiation tactics, and what to expect.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Victim to Victory: A Personal Injury Survival Guide (~$16), Written by a personal injury attorney, explains the full claims process, how insurance companies calculate settlements.
- Navigating Personal Injury Claims (~$14), Covers the pre-litigation claims process step by step, medical documentation, negotiation tactics, and what to expect.
Sources and References
The liability and insurance-claim principles here draw on authoritative legal and industry references: