 Lisa Anderson
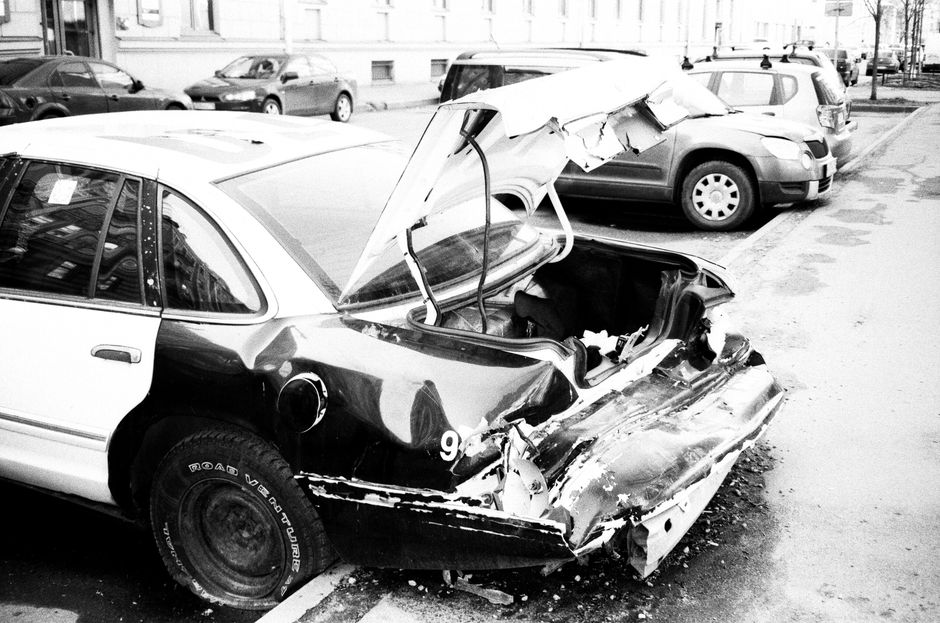
You’re sitting in the backseat of an Uber, heading home from a late dinner. The driver runs a yellow light, gets clipped by a pickup truck, and suddenly you’re being helped out of the car by a stranger while your shoulder throbs and your phone screen is cracked. In the chaos, someone asks if you’re okay and you say “I think so” because that’s what people say. Two days later, the shoulder is worse. You file a claim. And then you discover that getting compensated for a rideshare accident is nothing like filing a claim after a regular car crash.
I’ve seen this exact situation play out dozens of times. The injury is real, the liability seems obvious, and yet the claim turns into a months-long frustration because of how layered rideshare insurance actually works. Let me break down what you’re actually dealing with, what your rights are, and how to protect yourself starting right now.
Why Rideshare Claims Are More Complicated Than Regular Car Accidents
Most people assume that because Uber and Lyft are huge, well-funded companies, getting compensated after an accident involving one of their drivers should be straightforward. It isn’t. The reason comes down to one legal classification: Uber and Lyft drivers are independent contractors, not employees.
That matters enormously. Because drivers aren’t employees, Uber and Lyft aren’t automatically liable for their actions the way a trucking company would be liable for a driver on the clock. Instead, both companies have structured their insurance coverage in layers tied to what the driver was doing at the exact moment of the crash.
The Insurance Information Institute has documented how rideshare companies introduced a new category of coverage complexity that traditional auto insurance policies simply weren’t built for. Your standard insurer, the rideshare company’s commercial policy, and sometimes even a third-party driver’s insurance can all be involved in a single claim. Knowing which policy applies when is the first real obstacle you’ll face.
The Three Coverage Periods: This Is Everything
| Coverage Period | App Status | Driver Status | Bodily Injury Limit | Property Damage Limit | Notes |
|---|---|---|---|---|---|
| Period 0 | Off | Personal use only | Driver’s personal policy | Driver’s personal policy | Uber and Lyft provide no coverage |
| Period 1 | On, waiting | Logged in, no ride accepted | $50,000 per person / $100,000 per accident | $25,000 | Contingent coverage only; kicks in if driver’s personal insurance denies or is insufficient |
| Period 2 | On, trip accepted | En route to pick up passenger | $1,000,000 | $1,000,000 | Commercial liability policy active |
| Period 3 | On, passenger in vehicle | Passenger aboard | $1,000,000 | $1,000,000 | Full commercial liability coverage in effect |
Helpful resource: Fireproof Waterproof Document Bag for Medical and Legal Papers is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
Uber and Lyft both structure their insurance around what the industry calls “coverage periods.” Which period applies at the time of your crash determines how much money is potentially available to cover your injuries.
Period 0: App is off. The driver is just driving their personal vehicle. If they hit you, you’re dealing with their personal auto insurance policy only. Uber and Lyft have zero involvement.
Period 1: App is on, no ride accepted yet. The driver is logged in and waiting for a request. Coverage gets thin here. Both Uber and Lyft provide contingent liability coverage, typically $50,000 per person/$100,000 per accident for bodily injury, and $25,000 for property damage. That coverage only kicks in if the driver’s personal insurance denies the claim or doesn’t cover it fully.
Period 2: Ride accepted, driver en route to pick you up. The driver has accepted a trip and is heading to you. Here, Uber and Lyft’s $1 million commercial liability policy becomes active.
Period 3: Passenger in the vehicle. You’re in the car. The $1 million policy is fully in effect. This is the scenario most people imagine when they think “rideshare accident,” and it’s where coverage is most robust.
If you were a passenger in the rideshare vehicle, you were almost certainly in Period 3. That’s the good news. The messier scenarios involve pedestrians, cyclists, or other drivers hit by a rideshare vehicle in Period 1, when coverage is limited and the driver’s personal insurer may fight the claim hard.
What to Do Immediately After the Accident
The decisions you make in the first 24 to 72 hours have an outsized impact on your claim. I can’t stress this enough. What most people don’t realize is that the statements they make, the documentation they skip, and the treatment they delay can all be used against them later.
Here’s what to do, in order:
Call 911. Even if injuries seem minor. A police report creates an official record and documents the scene. Without it, the other side will dispute the facts.
Screenshot your app. Before you close the Uber or Lyft app, take a screenshot showing the trip details, driver name, vehicle information, and trip status. This is your proof of which coverage period applies.
Document the scene. Photograph everything: vehicle damage, license plates, road conditions, traffic signals, your visible injuries, and even the positions of the vehicles.
Collect information. Get the driver’s name, personal insurance info, and driver’s license number. Get contact information from any witnesses.
Seek medical attention the same day. Even if you feel okay. “I think I’m fine” is one of the most damaging things you can say in a personal injury claim. Soft tissue injuries, concussions, and internal injuries often have delayed symptoms. A gap between the accident and your first medical visit gives insurers ammunition to argue your injuries weren’t caused by the crash.
Report the accident through the app. Both Uber and Lyft have in-app accident reporting. Use it. This creates a timestamp and initiates the company’s own claims process.
Don’t give a recorded statement yet. An adjuster may call you quickly. You are not required to give a recorded statement to anyone, including Uber or Lyft’s insurer, before you understand your rights. Politely decline until you’ve consulted with someone.
Keeping organized records throughout the entire process will save you real money and headaches. A detailed injury and claim journal, something like a personal injury documentation workbook, can help you track medical visits, symptoms, missed work, and communications with insurers in one place. (As an Amazon Associate this site earns from qualifying purchases.)
Dealing With Uber and Lyft’s Insurance Companies
Here’s the part nobody wants to hear: the insurance companies working with Uber and Lyft are very good at their jobs. Their job is to resolve claims for as little money as possible. I spent 12 years as an adjuster. I know how this works from the inside.
When you report the accident, you’ll be assigned a claims representative. They’ll be polite. They’ll seem helpful. They might offer a quick settlement within days. That early offer is almost never in your best interest, especially if you’re still receiving medical treatment and don’t yet know the full extent of your injuries.
A few things to watch for:
The quick settlement offer. If an adjuster calls fast with a number, that’s not a courtesy. It’s a business decision. They want you to sign a release before you know what your medical bills will total.
Disputes about the coverage period. In Period 1 accidents especially, you may find Uber or Lyft arguing their commercial policy doesn’t apply and pushing you toward the driver’s personal insurer, who may simultaneously argue that driving for hire voids coverage.
Comparative negligence arguments. In many states, if you’re found even partially at fault, your compensation can be reduced. Insurers will look for any reason to assign you some percentage of blame.
Nolo’s personal injury resources explain that rideshare accident claims often involve multiple insurers negotiating among themselves, and injured passengers can get lost in that shuffle without an advocate. Knowing this going in helps you push back.
When to Talk to a Personal Injury Attorney
I never recommend specific attorneys, but I do strongly recommend consulting one, especially if you have injuries that required medical treatment, missed work, or caused any lasting limitation.
Here’s why: most personal injury attorneys who handle rideshare cases work on contingency, meaning they don’t get paid unless you do. That structure makes legal consultation essentially risk-free for you. Many offer free initial consultations.
An experienced attorney can help you:
- Identify every available insurance policy and coverage period
- Preserve evidence before it disappears (surveillance footage, app data, driver records)
- Handle communications with insurers so you don’t accidentally say something damaging
- Assess damages you might not think to claim, like future medical costs, lost earning capacity, or pain and suffering
- Fight back if Uber or Lyft’s insurer disputes coverage
The claims that seem simple often aren’t. And the claims that seem hopeless sometimes have significant value once a professional examines all the layers. If your injuries are serious, talk to someone before you sign anything.
The rideshare industry moved faster than insurance law was ready for, and injured people often pay that price in the form of confusing claims, delayed settlements, and undervalued injuries. You’re not being paranoid if you feel like the process is stacked against you. It kind of is. But understanding how the coverage layers work, documenting everything from minute one, and getting professional guidance before you sign anything puts you in a far stronger position than most people. You have more rights than the first phone call from an adjuster will suggest.
Sources & References
- Insurance Information Institute, Rideshare Insurance, explains rideshare insurance layers and coverage phases
- FTC, Gig Economy and Independent Contractors, independent contractor classification context
Photo: Aleksandr Neplokhov via Pexels
This article is for general informational purposes only and does not constitute legal advice. Laws vary by state. Consult a licensed personal injury attorney in your jurisdiction for advice specific to your situation. Most personal injury attorneys offer free consultations.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Victim to Victory: A Personal Injury Survival Guide (~$16), Written by a personal injury attorney, explains the full claims process, how insurance companies calculate settlements.
- Navigating Personal Injury Claims (~$14), Covers the pre-litigation claims process step by step, medical documentation, negotiation tactics, and what to expect.