 Rachel Thompson
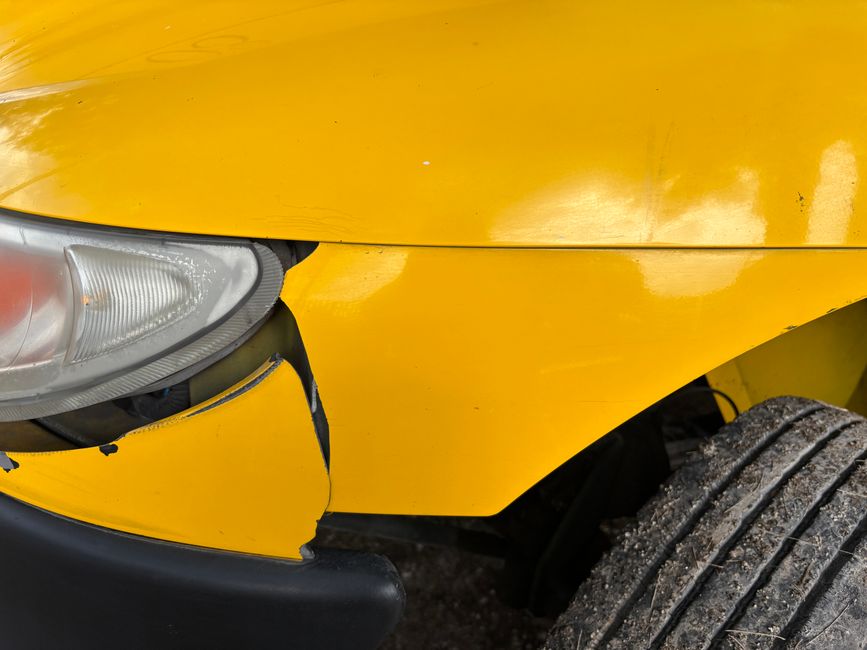
You’re sitting at a red light. Full stop. Then: impact. The other driver hit you from behind, and now your neck hurts, your car is crumpled, and someone at the insurance company is already calling to ask how you’re feeling. That call isn’t courtesy. It’s strategy.
Rear-end collisions are among the most common crashes on American roads, yet they produce some of the most disputed injury claims in the entire personal injury system. The reason: soft tissue injuries, the kind you almost always get from a rear-end hit, don’t show up clean on an X-ray. Insurance adjusters know this. They’re trained to move fast, offer early, and close the file before you fully understand what you’re dealing with.
I spent 12 years on their side of the table. Here’s what they don’t advertise.
Why Rear-End Settlements Are More Complicated Than They Look
The liability part is usually simple. In most rear-end accidents, the driver who hit you is at fault. Rear drivers are expected to maintain a safe following distance, full stop. Courts and adjusters both know this, so liability disputes are relatively rare. That clarity makes people assume the settlement will be quick and fair.
It usually isn’t.
The fight isn’t over who caused the crash. It’s over what the crash caused. Whiplash, herniated discs, thoracic strain, concussion, shoulder injuries from gripping the steering wheel: these are real, sometimes serious, and often slow to reveal themselves. Symptoms that feel like stiffness on day two can become chronic nerve pain by week six. Settling before that picture is clear is one of the most expensive mistakes a rear-end accident victim can make.
The Insurance Information Institute consistently notes that bodily injury claims take far longer to resolve than property damage claims, precisely because medical outcomes take time to stabilize. Yet insurers have every financial incentive to settle your bodily injury claim before that stabilization happens.
The Injuries That Drive Settlement Value
Helpful resource: Fireproof Waterproof Document Bag for Medical and Legal Papers is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
Settlement value in any personal injury claim comes down to damages, the legal term for everything you lost or suffered because of someone else’s negligence. In rear-end cases, damages generally fall into two buckets: economic and non-economic.
Economic damages are calculable losses:
- Medical bills (emergency room, imaging, physical therapy, specialist visits, prescriptions)
- Future medical costs if treatment is ongoing
- Lost wages from missed work
- Lost earning capacity if your injury affects your ability to work long-term
- Property damage to your vehicle
Non-economic damages are harder to quantify but often larger:
- Pain and suffering
- Emotional distress
- Loss of enjoyment of life
- Loss of consortium (impact on your relationship with a spouse)
The gap between a small settlement and a meaningful one almost always lives in the non-economic column. Adjusters minimize these because they can. They have no receipts to argue against.
One thing I’ve seen derail claims repeatedly: gaps in medical treatment. If you stopped going to physical therapy for three weeks because life got busy, the adjuster will argue your injuries weren’t serious enough to maintain consistent care. Continuity of treatment is documentation. Document everything.
What Actually Determines the Settlement Amount
80% of Injury Claims are WORTHLESS Because of This · JZ helps (a Florida injury law firm) on YouTube
There’s no universal formula, but these factors carry the most weight.
The severity and permanence of your injuries. A soft tissue strain that resolves in six weeks settles for far less than a cervical disc herniation requiring surgery. A traumatic brain injury changes the math entirely.
Maximum Medical Improvement (MMI). This is the point where your doctor says your condition has stabilized, meaning you’ve either recovered or reached a plateau. You should almost never settle a bodily injury claim before reaching MMI. You won’t know your full medical costs until you do.
Your state’s fault rules. Some states use pure comparative negligence, where you can recover damages even if you’re 99% at fault (though your recovery is reduced proportionally). Others use modified comparative negligence with cutoff thresholds, often 50% or 51%. A handful still use contributory negligence, which can bar recovery entirely if you’re even 1% at fault. If the other driver claims you stopped suddenly or your brake lights were out, these rules matter.
Insurance policy limits. If the driver who hit you carries only the state minimum in liability coverage, that cap is real. You can win a judgment larger than their policy, but collecting it from an individual with no assets is a different problem entirely. This is why uninsured/underinsured motorist (UM/UIM) coverage on your own policy exists.
Your own UM/UIM coverage. If you have it, it can step in when the at-fault driver’s policy isn’t enough. Check your declarations page tonight if you haven’t.
The quality of your documentation. Organized medical records, consistent treatment, a contemporaneous injury journal, photographs, witness statements: these aren’t just paperwork. They’re leverage.
A Step-by-Step Guide to Protecting Your Settlement Value
This isn’t a checklist you do once. It’s a sequence that matters.
1. Get medical attention immediately, even if you feel “okay.”
Adrenaline masks pain. Whiplash symptoms can be delayed 24 to 72 hours. A same-day visit to urgent care or an emergency room creates a medical record that begins on the day of the crash, not three days later when you finally can’t turn your head.
2. Don’t give a recorded statement to the other driver’s insurance company.
Not yet. Possibly not ever without legal representation. They will ask you how you’re feeling. They will ask questions designed to get you to minimize your pain or contradict yourself later. You’re not legally required to give one. Politely decline.
3. Report the accident to your own insurer.
This is different from giving a statement to the other driver’s carrier. Your own policy likely requires prompt notification. Do it, but be factual and measured. You don’t fully know the extent of your injuries yet.
4. Document your injuries and daily impact in writing.
Start a dated journal. Not dramatic prose: just facts. “Woke up at 2 a.m., neck pain 7/10, couldn’t get comfortable. Missed gym. Had trouble concentrating at work.” This becomes evidence of pain and suffering. A simple journal or a medical and injury record-keeping notebook can help you stay consistent. (Note: this site may earn a commission on purchases.)
5. Keep every receipt and every record.
Medical bills, pharmacy receipts, mileage to appointments, co-pays, any out-of-pocket cost tied to the injury. A medical records and claims organizer can make this manageable. (Note: this site may earn a commission on purchases.)
6. Wait for MMI before settling.
Repeat this one until it sticks. Once you sign a release, the claim is closed. If you settle for $4,000 and later need a $15,000 surgical procedure, the release you signed means you’re paying that out of pocket.
7. Consult a personal injury attorney before accepting any offer.
Most personal injury attorneys handle these cases on contingency, meaning you pay nothing unless they recover for you. The American Bar Association’s public education resources note that claimants represented by attorneys typically receive higher gross settlements than unrepresented claimants. An attorney also knows whether an offer is reasonable or insulting.
How the Settlement Process Actually Works
Once your medical treatment is complete or you’ve reached MMI, your attorney (or you, if you’re handling it yourself) will send a demand letter to the insurance company. This letter lays out the facts of the crash, the injuries, the treatment, the damages, and the amount you’re demanding to settle.
The insurer will respond with a counteroffer, almost certainly lower. Then negotiation begins. Most rear-end injury claims that go this route settle without litigation. The ones that don’t, where the insurer refuses to make a reasonable offer, may require filing a lawsuit. Lawsuits don’t automatically mean trial: the majority still settle before reaching a courtroom.
The timeline varies widely. A straightforward soft tissue claim with no complications might resolve in three to six months. A case involving surgery, long-term disability, or disputed liability can take two years or more.
One factor that complicates timing: medical liens. If your health insurance paid your medical bills, your auto insurance settlement may be subject to a lien, meaning a portion of your settlement goes back to reimburse your health insurer. Experienced attorneys negotiate these liens. It’s not optional paperwork.
The driver who rear-ended you set off a chain of consequences they probably didn’t intend. But intent doesn’t pay your medical bills or compensate you for the months you spent in physical therapy. The settlement process exists to make you whole, at least financially, and understanding how it works is the only way to make sure it does. Take your time, document everything, and don’t let urgency, yours or theirs, push you into a decision before you’re ready to make it.
This article is for general informational purposes only and does not constitute legal advice. Laws vary by state. Consult a licensed personal injury attorney in your jurisdiction for advice specific to your situation. Most personal injury attorneys offer free consultations.
Sources
- Fireproof Waterproof Document Bag for Medical and Legal Papers
- medical and injury record-keeping notebook
- medical records and claims organizer
- Nolo’s Plain-English Law Dictionary
- How to Win Your Personal Injury Claim by Joseph Matthews (Nolo)
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Victim to Victory: A Personal Injury Survival Guide (~$16), Written by a personal injury attorney, explains the full claims process, how insurance companies calculate settlements.
- Navigating Personal Injury Claims (~$14), Covers the pre-litigation claims process step by step, medical documentation, negotiation tactics, and what to expect.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Victim to Victory: A Personal Injury Survival Guide (~$16), Written by a personal injury attorney, explains the full claims process, how insurance companies calculate settlements.
- Navigating Personal Injury Claims (~$14), Covers the pre-litigation claims process step by step, medical documentation, negotiation tactics, and what to expect.
Sources and References
The liability and insurance-claim principles here draw on authoritative legal and industry references: