 Denise Wallace
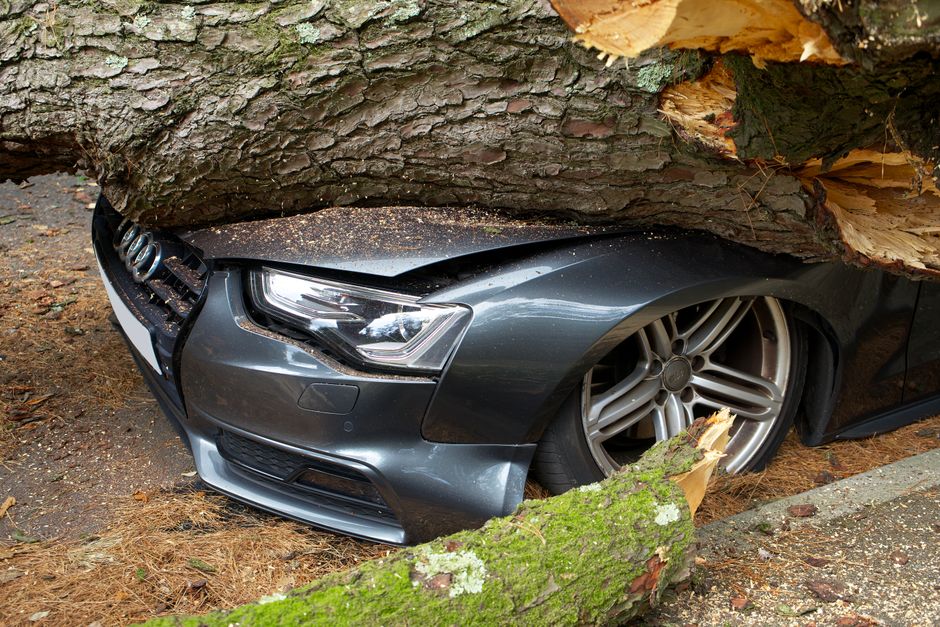
You’re sitting in a hospital waiting room, your neck stiff, your car totaled, and your phone buzzing with calls from an insurance adjuster who somehow already knows about your accident. That adjuster is friendly, sympathetic, and asking you to give a recorded statement “just to get the claim moving.” Here’s what you need to know right now: that call is not on your side. It’s the first move in a process that, if you’re not careful, can leave you settling for far less than your injuries actually cost.
Filing a car accident injury claim isn’t complicated, but it has real landmines. I spent 12 years on the insurance side before switching to help injury victims, and I can tell you the mistakes people make in the first 48 hours often haunt them for months. This guide walks you through the entire process, from the scene of the crash to the day you deposit a settlement check.
What to Do at the Scene and in the First 24 Hours
The decisions you make immediately after a crash shape everything that follows. Even if you feel fine, adrenaline masks pain. Whiplash or a herniated disc can take days to show up.
At the scene, focus on four things:
- Call 911. A police report creates an official, timestamped record of what happened. Without it, the other driver’s insurer can dispute basic facts like fault, location, and even whether a crash occurred.
- Get medical attention, even if you feel okay. Tell paramedics about every sensation, no matter how minor. “Mild neck stiffness” documented at the scene is evidence. Pain you mention for the first time three weeks later looks suspicious to adjusters.
- Collect information. The other driver’s name, license, insurance card, and plate number. Contact info for every witness. Photos of vehicle damage, skid marks, road conditions, traffic signs, and your visible injuries.
- Don’t say “I’m fine” or “it was probably my fault.” You genuinely don’t know either of those things yet.
Within 24 hours, go to an emergency room or urgent care if you haven’t already. Insurers scrutinize the gap between an accident and your first medical visit closely. Every additional day of delay weakens the connection between the crash and your injuries in their eyes.
Understanding Who You’re Filing Against (and Why It Matters)
Helpful resource: Pendaflex Portable File Box for Legal Documents is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
This surprises a lot of people: you may need to file with multiple insurance companies depending on your state and the circumstances of the crash.
The other driver’s liability insurance covers your injuries and property damage when they’re at fault. This is the most common claim path.
Your own insurance may also come into play in several situations. If the at-fault driver has no insurance or minimal coverage, your uninsured/underinsured motorist (UM/UIM) coverage kicks in. If your injuries are severe and the other driver’s policy limits are low, you might need both. You may also have medical payments coverage (MedPay) or personal injury protection (PIP) on your own policy, which pay your medical bills regardless of fault. According to the Insurance Information Institute, roughly 1 in 8 drivers on the road has no insurance at all, so your own UM coverage matters more than most people realize.
No-fault states work differently. In states like Florida, Michigan, and New York, you file with your own insurer first through PIP regardless of who caused the crash. You can only step outside that system and sue the at-fault driver if your injuries meet a certain threshold of severity. Knowing your state’s rules before you call anyone saves confusion and wasted time.
Building Your Claim: Documentation Is Everything
Here’s the unglamorous truth about personal injury claims: the side with better paperwork usually wins. The insurance company has a trained team organizing their evidence against your claim. You need to match that organization.
Learning how to document injuries after an accident is genuinely one of the highest-leverage things you can do for your case. A dedicated injury documentation journal, where you record your pain levels, missed activities, sleep disruption, and emotional state daily, gives your attorney and the adjuster a vivid picture of how the injury affected your life. Vague statements like “my back hurt for a few months” are worth far less than a journal showing 47 consecutive days of rated pain, missed work, and cancelled family commitments. A physical or digital journal kept from day one is a small effort with a potentially significant payoff. (You can find injury documentation journals and medical records organizers on Amazon that are specifically designed for this purpose; this site may earn a small commission on purchases.)
What to gather and keep:
- All medical records and bills from every provider you see
- Prescription receipts
- Pay stubs or employer letters confirming missed work (your lost wages claim is a real and recoverable part of your damages)
- Repair estimates and total loss documentation for your vehicle
- Your daily injury journal
- All correspondence with insurance companies, including emails and notes from phone calls with dates and times
Nolo’s personal injury resources at nolo.com offer straightforward guidance on organizing these records, and it’s worth reviewing before your first conversation with any adjuster.
Step-by-Step: How to Actually File the Claim
Once you’ve received medical attention and started documenting, here’s the practical sequence for filing:
Step 1: Notify your own insurance company. Do this even if the other driver is at fault. Most policies require prompt notification. You don’t have to say much, just that an accident occurred, you’re seeking medical treatment, and you’ll provide more information as you have it.
Step 2: Get the at-fault driver’s insurance information confirmed. Call their insurer to verify coverage is active. Get the claim number and the adjuster’s name assigned to the file.
Step 3: Decline the recorded statement. The other driver’s insurer will ask for one. You are not legally required to give it. Politely say you’re still receiving medical treatment and will provide information through proper channels. This isn’t about being difficult; it’s about not having your words used against you before you know the full extent of your injuries.
Step 4: Understand the demand letter process. Once your medical treatment is complete, or you’ve reached what’s called “maximum medical improvement” (the point where your condition has stabilized), you or your attorney sends a demand letter to the at-fault driver’s insurer. This letter outlines your injuries, your medical costs, your lost income, your pain and suffering, and the total amount you’re requesting. This formally opens negotiations.
Step 5: Negotiate, or have an attorney negotiate for you. The first offer you receive will almost always be lower than what your claim is actually worth. Understanding how insurance companies calculate settlements helps you see why their opening number is a starting point, not a final answer. Factors that increase settlement value include clear liability, documented ongoing treatment, and objective evidence of injury like imaging results.
Step 6: Evaluate any settlement offer carefully before signing. A signed release is permanent. Once you accept a settlement and sign the release, you typically cannot go back for additional compensation even if your injuries worsen or new medical problems emerge.
Should You Hire a Personal Injury Attorney?
Not every car accident claim requires a lawyer. A minor fender-bender with a few hundred dollars in medical bills and no lasting injury can often be handled directly with the insurer, especially if liability is clear.
But if any of the following apply to your situation, get a consultation before doing anything else:
- Your injuries required hospitalization, surgery, or specialist treatment
- You missed work, especially for an extended period
- The other driver disputes fault
- You’re being offered a settlement quickly and pressured to sign
- You have a pre-existing condition the insurer is using to minimize your claim
- The crash involved a commercial vehicle, rideshare car, or government vehicle
Personal injury attorneys typically work on contingency, meaning they take a percentage of your settlement (often 33% before trial, more if the case goes to litigation) and charge nothing upfront. The real question isn’t whether you can handle it yourself; it’s whether having professional representation will result in a meaningfully higher outcome even after the attorney’s fee.
For more context on what your claim might realistically be worth given your specific injury type, the overview at car accident settlement amounts by injury type gives useful reference points without creating false expectations.
The car accident injury claim process can feel overwhelming when you’re also trying to heal, get back to work, and manage the emotional aftermath of a crash. But the process has a logic to it, and understanding that logic is genuinely protective. Take the time to document carefully, don’t rush to accept early offers, and consult an attorney if your injuries are serious. The insurance company has professionals working this file every day. You deserve to walk into those negotiations just as prepared.
This article is for general informational purposes only and does not constitute legal advice. Laws vary by state. Consult a licensed personal injury attorney in your jurisdiction for advice specific to your situation. Most personal injury attorneys offer free consultations.
Sources
- Pendaflex Portable File Box for Legal Documents
- Insurance Information Institute
- nolo.com
- Leuchtturm1917 Hardcover Notebook for Personal Records
- Fireproof Waterproof Document Bag for Medical and Legal Papers
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Victim to Victory: A Personal Injury Survival Guide (~$16), Written by a personal injury attorney, explains the full claims process, how insurance companies calculate settlements.
- Navigating Personal Injury Claims (~$14), Covers the pre-litigation claims process step by step, medical documentation, negotiation tactics, and what to expect.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Victim to Victory: A Personal Injury Survival Guide (~$16), Written by a personal injury attorney, explains the full claims process, how insurance companies calculate settlements.
- Navigating Personal Injury Claims (~$14), Covers the pre-litigation claims process step by step, medical documentation, negotiation tactics, and what to expect.