 Jennifer Harris
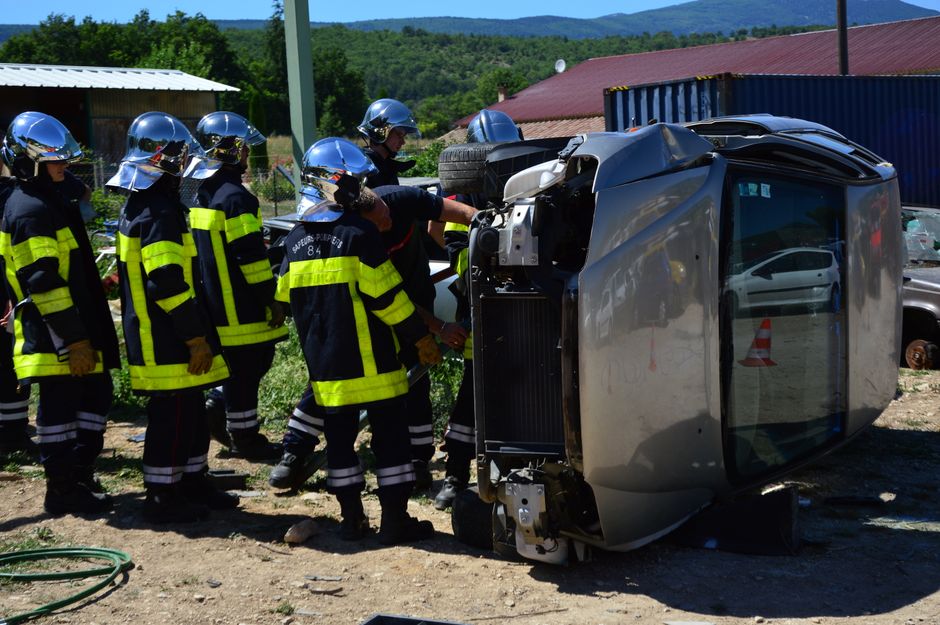
One in eight drivers on American roads today carries zero liability insurance. That’s not a rounding error, it’s roughly 33 million people, according to the Insurance Research Council’s most recent estimates. If one of them hits you this afternoon, the standard advice you’ll find online (“call the police, exchange information”) covers maybe 20% of what you actually need to do.
The rest? Most articles skip it entirely. Let me fill in the gaps.
I spent 12 years on the adjuster side of this equation, which means I watched a lot of injured people make the same four or five mistakes in the first 72 hours after a crash, mistakes that cost them real money later. Not because they were careless. Because nobody told them what the insurance company was actually looking for, and what their own policy quietly covered.
- 1 in 8 U.S. drivers is uninsured; your own UM/UIM coverage is your primary financial shield.
- Call police even for minor crashes, an official report is often required to trigger UM claims.
- Document everything at the scene: photos, witness names, the other driver's plate and face.
- UM/UIM claims must typically be filed within 30 days; missing that window can void coverage entirely.
- An uninsured driver can still be sued personally, but collecting is a separate, harder problem.
The Number That Should Scare You a Little
The IRC puts the national uninsured driver rate at around 14% as of this year, but that average conceals wild variation by state. In Mississippi, roughly 1 in 4 drivers has no coverage. Florida sits near 20%. If you’re in California, Oklahoma, or Tennessee, you’re not far behind.
What this means practically: the lower your state’s rate, the less likely you’ll ever need this information. But if you live in the Sun Belt or the South, this isn’t a remote contingency. It’s a legitimate weekly risk.
The CDC’s injury data reinforces the stakes: motor vehicle crashes are among the leading causes of injury-related emergency department visits in every age group under 65. A sizable slice of those crashes involve uninsured or underinsured drivers, and the injured party’s out-of-pocket burden, absent the right coverage, can run well into five figures before litigation enters the picture.
What to Do in the First 30 Minutes
Helpful resource: Leuchtturm1917 Hardcover Notebook for Personal Records is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
This is where people lose their cases before they even know they have one.
Step 1: Do not let the other driver talk you out of calling police. I can’t count how many claims I reviewed where the uninsured driver said something like “let’s keep this between us” or “I’ll pay you cash.” They almost never do. And without a police report, you’ll have a brutal time filing a UM (uninsured motorist) claim later. Most insurers require it. Call 911, or drive to the nearest precinct if it’s a minor impact and the vehicles are movable.
Step 2: Photograph everything before you move anything. Both vehicles from four angles. The other driver’s license plate. Their face (yes, really, people flee). The VIN visible through the windshield if you can get to it. The road conditions, skid marks, traffic signals. Your phone’s GPS metadata will timestamp and geolocate each photo automatically. Adjusters love this.
Step 3: Get witnesses. Not just their contact info, ask them to briefly record a voice memo on your phone describing what they saw. People’s memories degrade fast, and a 45-second audio clip recorded at the scene carries more weight than a statement given three weeks later.
Step 4: Seek medical attention the same day. Even if you feel fine. Adrenaline is a hell of a drug, and whiplash symptoms classically appear 24 to 72 hours after impact. A gap between the crash and your first medical visit gives adjusters ammunition to argue your injuries weren’t caused by this accident. Go to urgent care or an ER that evening.
Your Own Insurance Is the Real Answer Here
Here’s where most people’s understanding falls apart. They think “the other driver has no insurance, so I’m stuck.” You’re probably not, if you have the right coverage.
Uninsured Motorist (UM) coverage pays for your injuries when the at-fault driver has no liability insurance. Underinsured Motorist (UIM) coverage kicks in when the other driver’s policy limit is too low to cover your damages. In many states, insurers are required to offer both. In a handful of states (including New Hampshire and Virginia, historically), you can waive them. Waiving them is almost always a mistake, and I say that having watched the premium difference up close, it’s rarely more than $15 to $40 a month.
UM/UIM typically covers:
- Medical expenses and lost wages
- Pain and suffering (in most states)
- Funeral expenses in a wrongful death scenario
- Property damage in some states (UMPD, a separate sub-coverage)
What it does NOT cover: damage to your vehicle in states without UMPD, and anything beyond your policy’s per-person or per-accident limits.
One critical procedural trap: most insurers require you to notify them of a UM claim within 30 days of the accident. Some policies say “promptly,” which courts have interpreted as few as 10 to 14 days. Don’t sit on this. Call your own insurer on the day of the crash, even if you’re not sure yet that the other driver is uninsured. You can always cancel the claim. You can’t always add it later.
What Your Coverage Options Actually Cost
This table reflects typical national ranges for adding UM/UIM coverage to a standard personal auto policy as of July 2026. Your exact premium depends on your state, driving record, and existing limits.
| Coverage Type | Typical Annual Add-On Cost | What It Covers | Worth It? |
|---|---|---|---|
| UM Bodily Injury (25/50) | $60 – $140/year | Injuries up to $25k/person, $50k/accident | Baseline minimum; get higher if you can |
| UM Bodily Injury (100/300) | $120 – $280/year | Injuries up to $100k/person, $300k/accident | Strong protection for most drivers |
| UIM Bodily Injury (100/300) | $80 – $200/year | Bridges gap when at-fault driver is underinsured | Yes, especially in high-uninsured states |
| UMPD (Property Damage) | $30 – $80/year | Vehicle damage by uninsured driver | Depends on your collision deductible |
| Collision (standalone) | $200 – $900/year | Your vehicle regardless of fault | Redundant with UMPD but covers more scenarios |
The math is blunt. A serious injury claim can produce medical bills of $40,000 to $150,000 or more. Paying an extra $200 a year to protect against that isn’t insurance industry fear-mongering, it’s arithmetic.
Suing an Uninsured Driver: Honest Expectations
You can sue. Winning isn’t the hard part. Collecting is.
If someone’s driving without insurance, odds are strong they don’t have significant assets to garnish. Attorneys call this being “judgment-proof.” You go to court, you win a $75,000 judgment, you try to garnish wages, and you discover the defendant earns $11 an hour with no bank account worth attaching. A judgment you can’t collect is just expensive paper.
That said, it’s not always hopeless. A few scenarios where suing makes sense:
When the at-fault driver has identifiable assets (owns property, has a visible income stream), litigation or a structured settlement threat can shake loose real money. When the accident involved a commercial vehicle operated by someone who’s personally uninsured but whose employer carries coverage, the employer’s policy may be reachable. When a third party is partly liable, a municipality for dangerous road conditions, a bar under dram shop liability laws, that defendant likely has collectible insurance.
I spoke with a woman in Phoenix two years ago, I’ll call her Rosa, who was rear-ended at a stoplight by a 24-year-old with no insurance and no assets. Her UM claim paid $47,000 toward her medical bills and lost wages. She filed suit against the driver anyway on the advice of her attorney, and three years later, when the driver landed a software job and bought a condo, the existing judgment allowed her to attach wages. She eventually collected another $18,000. Rare outcome. But not impossible.
The Specific Paperwork That Will Haunt You If You Skip It
When I was adjusting claims, the file that walked in organized was the one that settled faster. Not because adjusters are soft-hearted, but because a well-documented claim is harder to chip away at.
Keep a folder (physical or digital) containing:
- The police report number and a copy as soon as it’s available (usually 3 to 7 business days after the crash)
- Every medical receipt, bill, and Explanation of Benefits from your health insurer
- A daily pain and function journal starting the day after the crash (one of the most underused tools I’ve ever seen, jurors and adjusters both respond to specifics: “couldn’t lift my left arm above shoulder height,” not “was in pain”)
- Mileage logs for every medical appointment
- Documentation of missed work, ideally a letter from HR or your direct supervisor on company letterhead
- All correspondence with your insurer, dated
If you want a ready-made system, an injury documentation journal or medical records organizer can help you stay consistent, especially during a stressful recovery period. (This site may earn a small commission if you purchase through a link here.)
The American Bar Association’s public resources on personal injury rights are worth 30 minutes of your time if you’re navigating this without an attorney yet. They’re not a substitute for legal counsel, but they’ll help you understand the vocabulary before you walk into any conversation.
Sources
- Insurance Research Council: Uninsured Motorists study, tracking state-by-state uninsured driver rates and trends through 2026
- CDC WISQARS Injury Data: Web-based Injury Statistics Query and Reporting System, motor vehicle injury epidemiology by age and severity
- National Association of Insurance Commissioners (NAIC): Consumer guidance on UM/UIM coverage requirements by state
- American Bar Association Public Education: Plain-language resources on personal injury rights and legal process
- Insurance Research Council (2023): “Uninsured Motorists” report, foundation for 1-in-8 national statistic and state-level variance data
Photo: Ulrick Trappschuh via Pexels
This article is for general informational purposes only and does not constitute legal advice. Laws vary by state. Consult a licensed personal injury attorney in your jurisdiction for advice specific to your situation. Most personal injury attorneys offer free consultations.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Victim to Victory: A Personal Injury Survival Guide (~$16), Written by a personal injury attorney, explains the full claims process, how insurance companies calculate settlements.
- Navigating Personal Injury Claims (~$14), Covers the pre-litigation claims process step by step, medical documentation, negotiation tactics, and what to expect.